

Subscription Manager - ReSubs

- 39.00 Reviews
- 3.6
- Downloads
- 50,000+
Our take on Subscription Manager - ReSubs from Appgk
I approached Subscription Manager - ReSubs as the sort of finance app you open when recurring payments have started blending into the background. After a short time using it, my impression is that its value is less about replacing a banking app and more about giving subscriptions their own place to be reviewed. That distinction matters: it can help you notice services you no longer use, but it still depends on you checking the information carefully before cancelling anything.
ReSubs is a free Android app from Christian Krueger, aimed at tracking, managing, and cancelling subscriptions. It is listed for Everyone and works on Android 8.0 or later. The current version is 1.37.0, and the app has passed the early discovery stage with over fifty thousand installs. Its average rating sits at 3.6 from roughly a thousand ratings, which suggests a useful but not universally smooth experience. I think that is a fair starting point: this is a practical tool with a clear purpose, not a complete personal-finance system.
How ReSubs fits into everyday money management
The central idea is simple. Instead of relying on memory, email searches, or scattered bank notifications, you create a visible record of the subscriptions that leave your account. That record gives you a place to review renewal timing, recurring costs, and services that have quietly become unnecessary. For someone who has a streaming service, a cloud plan, an app membership, and a few trial conversions running at once, that overview can be more useful than another general budgeting dashboard.
I found the strongest use case to be a monthly subscription check rather than constant monitoring. Open the app around the same time you review your bank statement, compare each entry with the actual charge, and remove anything you no longer recognize or use. This workflow turns ReSubs into a small financial maintenance habit. It does not need to be opened every day to be worthwhile.
Best Parts of Subscription Manager - ReSubs
Things to Keep in Mind About Subscription Manager - ReSubs
A realistic example is a household where one person starts a free trial, another renews a fitness service, and a shared account continues paying for storage after a device change. None of those charges is necessarily large on its own. The problem is that they are easy to overlook when they arrive on different dates. ReSubs gives those commitments a common list, making the total pattern easier to question.
What the app does well for subscription-heavy users
The app’s focus is its biggest strength. Traditional banking apps show transactions, but they often do not explain whether a payment is a subscription, a one-off purchase, or a price change. A general budgeting app may categorize recurring spending, yet still bury the details among groceries, transport, and bills. ReSubs is more direct: it asks you to think specifically about ongoing commitments.
News and Features Related to Subscription Manager - ReSubs

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
That focus also makes it suitable for people who dislike complicated financial software. You do not need to build a full household budget before getting something useful from it. Start with the services you know, add the uncertain ones as you encounter them, and use the list as a prompt for further checking. I would particularly recommend this approach after changing banks, replacing a phone, or reviewing a long-unused email account.
Another useful habit is to record the reason for keeping a subscription, not merely its name. If a service is retained for work, family sharing, backup, or a particular seasonal need, that context helps when the next review comes around. If you cannot explain why an entry remains active, it deserves a closer look. ReSubs works best when treated as a decision aid rather than a passive catalogue.
Don't want to read the full review?
Where it differs from banking apps and full budget tools
ReSubs is narrower than a bank app, and that is both its advantage and its limitation. A bank application normally offers real transaction history and may let you dispute or block payments, while ReSubs is better understood as a dedicated planning and review layer. If you need authoritative account balances, fraud controls, transfers, or detailed spending categories, your bank remains the more appropriate tool.
Full budgeting apps are usually stronger when you want income planning, envelopes, debt tracking, investment views, or shared household finances. They may also reduce manual work by connecting directly to accounts, depending on the service and region. ReSubs is more appealing when that wider system feels excessive and your immediate concern is simply, “What recurring services am I still paying for?”
Screenshots
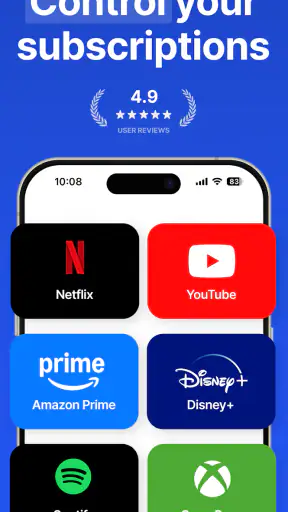
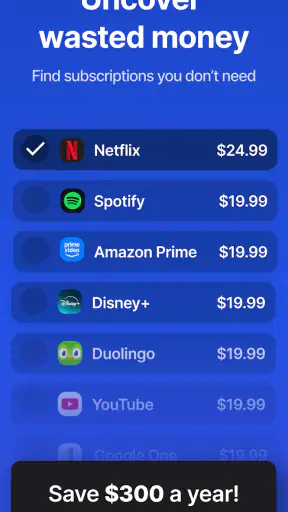
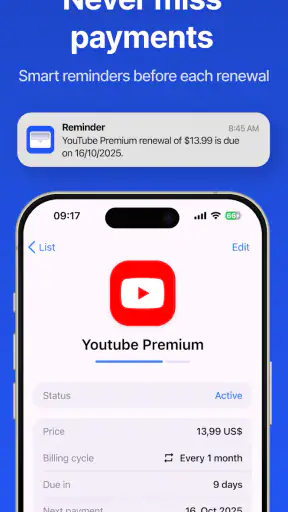
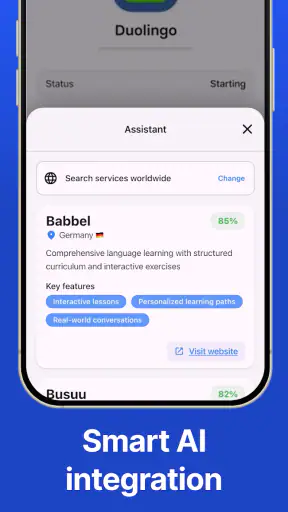
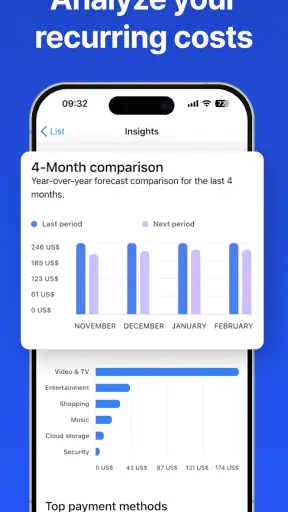
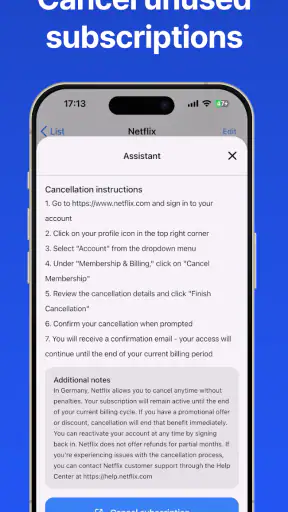
There is a useful middle ground between those choices. I would use the banking app to confirm what actually left the account, ReSubs to maintain a readable subscription list, and a broader budget tool only if recurring payments are part of a larger financial plan. Keeping those roles separate reduces the risk of treating a manually maintained list as proof that a charge has been cancelled.
What changed, how it affects users, and what still needs attention
The current release and the product’s direction
The current release, 1.37.0, shows that the project is being maintained rather than abandoned after launch. The app was released on September 24, 2024, so its development is still relatively recent. That is encouraging for users who want a focused utility that may continue to be refined, although a version number alone should not be mistaken for a guarantee of a particular feature or workflow.
From a user’s perspective, the important point is that ReSubs appears to be evolving around a defined problem instead of trying to become an all-purpose finance platform. That can produce a cleaner experience, but it also means progress should be judged by small improvements to subscription review, accuracy, and cancellation guidance. I would rather see those fundamentals become dependable than see unrelated financial features added simply to make the app look broader.
Existing users should approach updates with a practical routine. Before installing a new version, keep your own note of important subscriptions and renewal dates. After updating, quickly check that your entries still make sense and that any labels or dates you rely on remain clear. This is not because a problem is known; it is simply sensible practice for any app that stores information you use to make financial decisions.
Manual accuracy is the hidden trade-off
The most important limitation is also the easiest to miss: a subscription manager is only as reliable as the information it contains. If a price changes, a billing cycle shifts, a family member cancels a plan, or a payment method is replaced, your list can become outdated. The app can help you notice and organize commitments, but it should not be treated as an automatic ledger unless the specific workflow you use clearly verifies charges.
My advice is to compare entries with receipts, account history, or the service’s own billing page. Pay special attention to annual plans, introductory offers, and subscriptions billed through an app store rather than directly by the provider. These are the cases where a remembered monthly amount can be misleading. A good record should include the billing interval and the account responsible for the charge, not just a familiar brand name.
This creates a trade-off with automated alternatives. Account-connected tools can save time and may identify recurring payments without manual entry, but they can raise questions about access, categorization, and missed or misidentified charges. A focused manual tracker requires more discipline but can give you more control over what you record. For privacy-conscious users, that difference may be more important than convenience.
Cancellation is not the same as deleting an entry
The phrase “manage and cancel” can easily lead to the wrong expectation. Removing a subscription from a tracking list is not automatically the same as ending the underlying contract. Cancellation normally has to be completed through the service that bills you, an app-store subscription screen, or another official channel. After doing that, keep the entry visible until the final payment and access period are finished, then mark it as ended or remove it according to your preferred record-keeping method.
This two-step process is one of the most useful ways to avoid mistakes. First confirm where the subscription is billed. Then cancel it through that channel and save the confirmation. Finally, check the next statement. ReSubs can serve as the reminder and checklist, but the provider’s confirmation is what matters when you need evidence that renewal has stopped.
I would also avoid cancelling a service immediately just because you do not recognize its name. Some providers use a parent company or payment descriptor that differs from the product name. Match the amount, date, email receipt, and account owner before taking action. That extra minute is worthwhile, especially when several people share payment responsibilities.
Who should use it and who should choose something else
ReSubs suits people who have recurring charges spread across several services and want a dedicated place to review them. It is also a good fit for anyone who finds full budgeting apps intimidating, or for users who prefer to keep financial records manually instead of connecting accounts. Students, families, freelancers, and people who regularly start trials can all benefit from a simple subscription-focused checklist.
I would be more cautious about recommending it to someone who expects automatic discovery, real-time account synchronization, or a complete financial command center. If your main goal is to reconcile every transaction, monitor cash flow, or manage investments, a banking or budgeting platform will likely serve you better. ReSubs is not the right first choice for someone unwilling to maintain entries or verify charges independently.
It may also be a poor fit if you share all subscriptions across a household but have no agreed process for updating the list. In that situation, the record can become confusing quickly. Decide who adds a new service, who confirms cancellations, and whether the list represents one person’s payments or the whole household. The app cannot solve unclear ownership by itself.
Cost, access, and sensible expectations
The app is free to install, which makes it easy to test without committing money at the outset. In-app purchases range from $1.99 to $49.99 per item, so I would review the purchase screen carefully before enabling anything beyond the free experience. The important question is not simply whether the app costs nothing to download, but which functions you personally need and whether they justify an optional purchase.
Because it supports Android 8.0 and later, it remains accessible on many older devices. That is useful if you are trying to manage finances without buying a new phone. On the other hand, older hardware can make any organizational app feel less comfortable, particularly when entering many records at once. I would begin with a small set of active subscriptions and expand only after the workflow feels natural.
The Everyone age rating also makes the app broadly approachable, but an age rating does not replace financial judgment. A younger user can use a list like this to understand recurring spending, while an adult should still handle account credentials, payment decisions, and cancellation confirmations responsibly.
Three practical workflows that make the app more useful
Use a discovery pass before a cleanup pass. First collect every recurring service you can find from bank history, email receipts, and app-store account pages. Do not cancel during this first pass. Once the list is complete, review duplicates, unused services, and plans with unclear ownership. Separating discovery from decisions reduces impulsive cancellations and missed subscriptions.
Record renewal context, not only the amount. Note whether a charge is monthly, annual, shared, or tied to a temporary promotion. This makes the list more useful when the amount changes or a renewal appears months later. It also prevents an annual plan from looking like an unexplained one-time charge.
Keep cancelled entries until the billing cycle proves the result. A cancellation confirmation can still be followed by a final permitted charge or an already-open access period. Leaving the item in a review state gives you a prompt to check the next statement. Only then should you consider the process complete.
These workflows reveal the app’s real role. It is not a magic detector for every forgotten payment; it is a structured place to turn scattered evidence into decisions. The more carefully you set up the record, the more useful the review becomes. If you enter vague names and never revisit them, the app will eventually become another neglected list.
What I would watch as development continues
For future updates, I would pay attention to improvements that reduce uncertainty without hiding the manual nature of the tool. Clearer renewal reminders, easier editing after a price change, and a dependable way to distinguish active, paused, trial, and cancelled entries would all make the review process safer. I would also value guidance that helps users identify the correct cancellation channel without suggesting that removing a record ends a contract.
Privacy and control are another area worth watching. Users deciding between ReSubs and an account-connected alternative will want to understand how much work stays on the device, what information is required, and whether optional purchases change the workflow. I am not treating any particular future behavior as promised; these are simply the questions that matter when a finance app becomes part of a regular money routine.
The rating of 3.6 indicates that prospective users should try the workflow with a limited set of subscriptions before investing substantial time in a complete catalogue. That is a sensible test for any organizational app. Add a few known services, compare the result with your actual account history, and see whether the editing and review process feels clear enough for you to maintain.
My final view is positive but measured. ReSubs is most valuable as a focused subscription review habit, not as a replacement for your bank or a full budgeting system. It can help expose forgotten commitments, organize renewal information, and make cancellation decisions less abstract. Its weaknesses come from the same focused design: manual records need care, and deleting an item should never be confused with ending a billing agreement.
If recurring payments are the specific problem you want to solve, I think it is worth trying, especially because the download is free and the Android requirements are modest. If you need automatic account analysis or broad financial planning, choose a tool built around those priorities instead. For the right user, Subscription Manager - ReSubs is a useful checkpoint between noticing a charge and deciding whether that charge still deserves a place in your life.
Subscription Manager - ReSubs FAQ
What is Subscription Manager - ReSubs used for?
Subscription Manager - ReSubs is designed to help you organize and monitor recurring subscriptions in one place. You can record services such as streaming platforms, cloud storage, software, memberships, and other regular payments. The app can make it easier to see upcoming renewal dates, review your recurring expenses, and avoid forgetting about subscriptions you no longer use. It is primarily a tracking and planning tool rather than a replacement for the billing systems of individual services.
Can Subscription Manager - ReSubs cancel subscriptions automatically?
You should not assume that Subscription Manager - ReSubs can cancel every subscription directly. In most cases, cancellation must still be completed through the service provider, Google Play, Apple App Store, website, or payment account where the subscription was originally purchased. ReSubs can help you identify subscriptions and remember renewal dates, but you should open the relevant provider’s account settings and confirm the cancellation there. Always check for a confirmation message after cancelling.
Does ReSubs connect to my bank account or automatically detect payments?
Subscription Manager - ReSubs is generally intended for manually managing subscription information, so users should review the app’s current permissions and features before expecting automatic bank synchronization. If you enter subscription names, prices, billing cycles, and renewal dates yourself, the accuracy of the information depends on those entries. Avoid sharing banking credentials unless the app clearly explains a secure, trustworthy integration and you are comfortable with its privacy terms.
Is Subscription Manager - ReSubs free to use?
The availability of free features, premium tools, advertisements, or in-app purchases may depend on the version of Subscription Manager - ReSubs and the platform where it is downloaded. Before installing or upgrading, check the official store listing for pricing, trial conditions, and recurring charges. If a trial is offered, note its end date and cancellation requirements. Reviewing these details helps prevent unexpected fees and clarifies which tracking features are included without payment.
Is my subscription information private and secure in ReSubs?
Before adding sensitive financial details, read Subscription Manager - ReSubs’s privacy policy and examine the permissions requested by the app. Subscription records may include service names, prices, renewal dates, and personal notes, so it is important to understand whether information is stored locally, synchronized online, or shared with third parties. Use a strong device lock, keep the app updated, and avoid entering passwords, card numbers, or other credentials unless absolutely necessary.











